If your health plan just stopped paying for Ozempic, Wegovy, Zepbound, or Mounjaro, you are part of one of the biggest health-benefit stories of the year. Employers and insurers are dropping GLP-1 weight-loss coverage at a fast clip in 2026, and without a plan behind you, list prices can run well over a thousand dollars a month. This guide breaks down why coverage is disappearing, what it actually costs now, and how to build an appetite-management plan that does not live or die by a single insurance decision.
Why Are So Many Americans Losing GLP-1 Coverage Right Now?
Employers and insurers are pulling back because GLP-1 drugs have become one of the fastest-growing line items in corporate health spending. Coverage for GLP-1s to treat obesity dropped from 72% of surveyed employers in 2025 to 60% in 2026, according to a Business Group on Health survey of 127 employers representing 8.7 million covered individuals. Cigna made headlines when it stopped covering GLP-1s for weight loss through its own employee health plan on July 1, and PepsiCo followed by cutting GLP-1 coverage for employees due to rising costs while keeping it for diabetes. Mercer's analysis put numbers behind the trend, noting that GLP-1s approved for weight loss, priced over $1,000 per month before rebates, have become two of the fastest-growing contributors to pharmacy spend. None of this is about whether the drugs work. It is a benefits-budget decision, and it is happening plan by plan, often with little warning to the person relying on the prescription.
How Much Does a GLP-1 Cost Without Insurance?
Without insurance, a brand-name GLP-1 can run anywhere from a few hundred dollars to well over a thousand a month, depending on the drug and where you fill it. The sticker price of a brand-name GLP-1 is roughly $1,000 to $1,350 per month at list price. Manufacturers have tried to soften the blow with direct-to-consumer programs — NovoCare Pharmacy and LillyDirect sell the drugs for roughly $199 to $449 a month depending on dose and offer — but that is still a real monthly bill for most households. And the scale of the shift is large: from 2025 to 2026, 12 million people were on plans that dropped coverage for Zepbound and 12 million had plans that dropped Wegovy, according to GoodRx research. If you are staring at a denial letter right now, you are in very large company.
What Are Your Options If Your Coverage Just Got Cut?
You generally have four paths, and none of them involve a snap decision. First, appeal. Ask your prescriber to document the medical reason for treatment and request the plan's exact exclusion language before you assume there is nothing to be done. Second, look at manufacturer cash-pay programs, which can bring costs down substantially compared to retail pharmacy pricing. Third, be cautious with compounded versions sold outside a licensed pharmacy relationship — the FDA issued more than 55 warning letters to online sellers of compounded GLP-1 medications in September 2025 over misleading marketing, and oversight in this space keeps tightening. Fourth, talk to your prescriber about whether tapering, spacing doses, or switching strategy makes sense for you — this is a conversation for your healthcare provider, not a DIY decision.
- Request the plan's written exclusion policy and consider a formal appeal
- Compare manufacturer direct-pay programs before paying full retail price
- Avoid unregulated compounded products sold through ads or social media
- Loop in your prescriber before changing dose, frequency, or medication
Where Herbal, Appetite-Habit Support Fits In
Herbal support is not a replacement for a prescription, and it never claims to be. What it can do is meet you in the everyday moments a medication does not touch — the 3 p.m. craving, the mindless second helping, the stress snack. Korean herbal medicine has spent centuries refining exactly this kind of gentle, whole-body support: hanbang is the traditional Korean medical system, holistic medicine documented since the 7th century, built on combinations of botanicals used consistently over time rather than a single silver-bullet compound. That is the lane VYNEHERB works in — structure-and-function herbal formulas designed to support appetite habits and metabolism day to day, whether you are on a GLP-1, coming off one, or navigating a coverage gap in between.
Building a Plan That Isn't Tied to Your Insurance Card
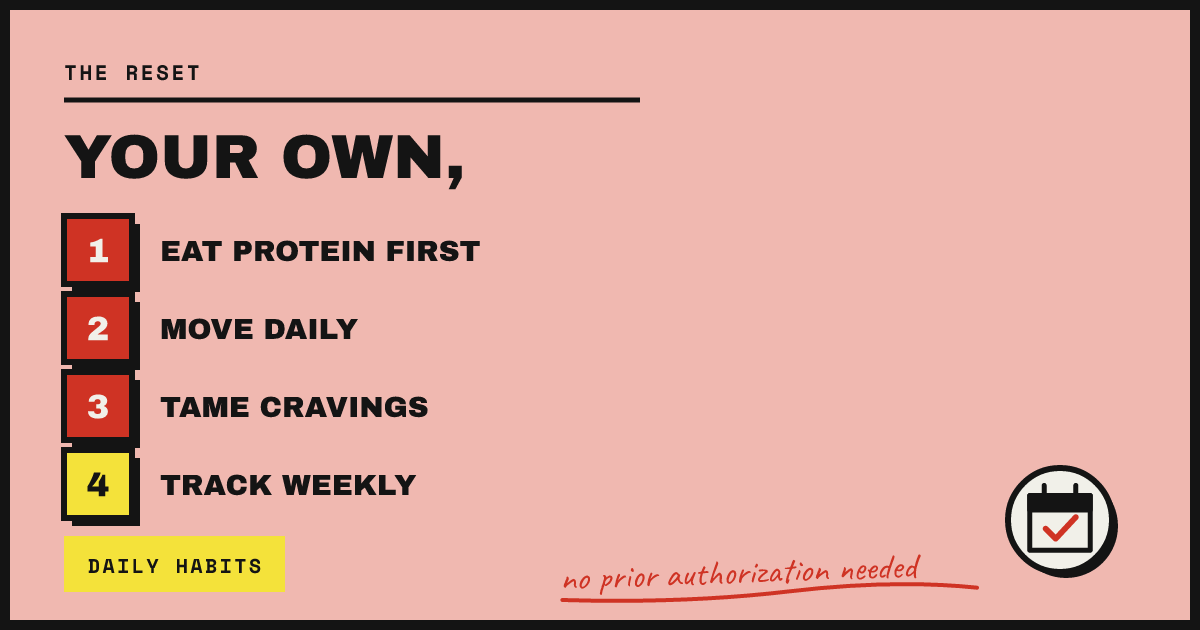
The most durable weight-management plan is the one that keeps working no matter what your benefits document says next year. That means protein-forward meals, daily movement you actually enjoy, a plan for cravings before they hit, and a way to track how your habits are trending week to week — not just what a scale says. If you want a structured place to start rebuilding those habits without waiting on a prior authorization, our 14 Days Fast Weight Loss Program lays out a clear, day-by-day framework you can follow on your own timeline. It will not replace a conversation with your doctor about medication, but it gives you something concrete to control while the insurance landscape keeps shifting.
Frequently Asked Questions
Can I switch to a cheaper GLP-1 if my plan drops coverage?
Sometimes. Some plans steer patients toward a different covered GLP-1 instead of dropping the category entirely, but availability varies by insurer and formulary. Always confirm with your prescriber and plan before switching anything yourself.
Is it safe to buy a compounded GLP-1 online to save money?
Regulators have flagged real safety and quality concerns with unregulated compounded versions sold through telehealth ads and social media. Talk to a licensed healthcare provider before considering any option outside a standard pharmacy prescription.
Do herbal supplements work the same way as GLP-1 drugs?
No. Herbal supplements are not equivalent to prescription GLP-1 medications and are not designed to treat, cure, or prevent any disease. They are meant as gentle, daily support for appetite habits and general wellness, and they work best alongside a healthy diet, movement, and guidance from your healthcare provider.